Saving $10k in a year sounds huge, doesn’t it?
I get it. When I first started my money journey, I was drowning in debt and living paycheck to paycheck. The idea of saving five figures felt like something only “rich people” could pull off. Spoiler alert: it isn’t.
I went from $90,000 in debt to saving my first $100,000 by my mid-20s — and it all started with repeatable, low-friction systems. No magic tricks. No depriving yourself of every little joy in life. (I am never going to tell you to give up your favorite morning coffee! ☕)
All you need is a clear, automated plan and the decision to start. Below is your complete step-by-step savings challenge plan, a free printable progress tracker, and real-world strategies that work even on a modest or irregular income.
⚡ The $10,000 Math in a Nutshell
Nobody saves $10,000 all at once. You save it in bite-sized increments: $833.33 per month, $384.62 bi-weekly, $192.31 per week, or just $27.40 per day. Automating a weekly transfer into a high-yield savings account makes this goal completely achievable.
🎁 Free Printable $10k Savings Challenge Tracker
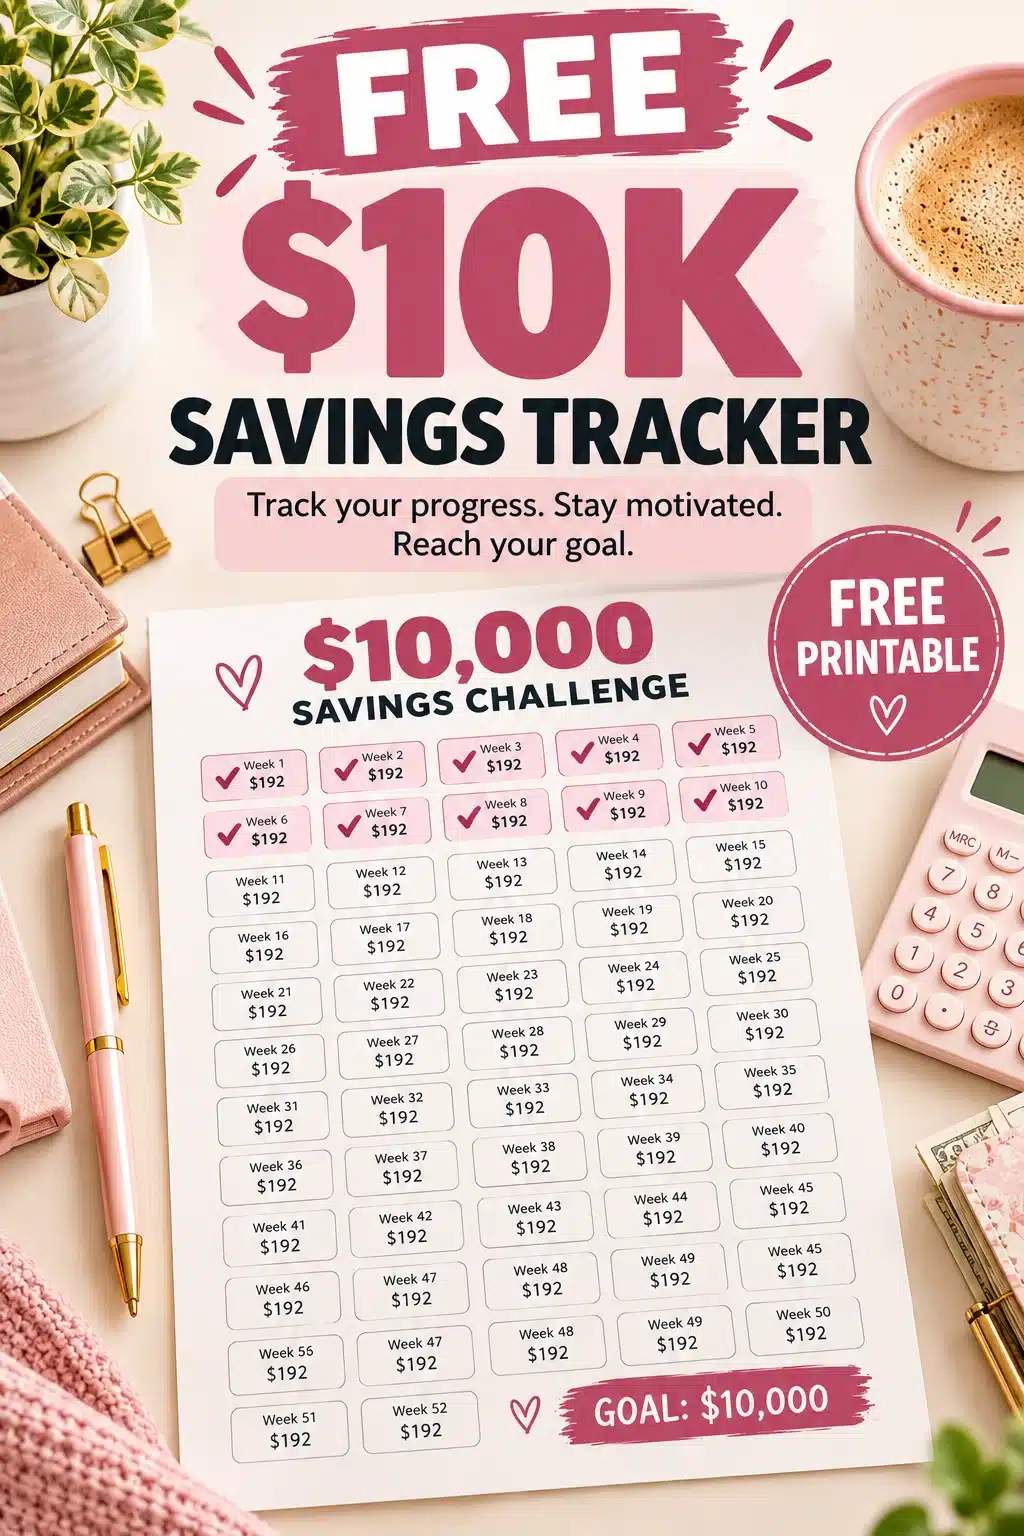
Color in one progress block each week as you hit your milestones. Watching your tracker fill up is the ultimate motivation booster!
📋 In This Guide
+
- Is It Actually Possible to Save $10,000 in a Year?
- The Math: Breaking $10k Into Bite-Sized Goals
- Step 1: Create a Realistic Budget (50/30/20 Rule)
- Step 2: Audit Your Spending & Plug Money Leaks
- Step 3: Pay Yourself First (Automate Into a HYSA)
- Step 4: Cut Sneaky Expenses Without Cutting Joy
- Step 5: Earn More (Side Hustles & Digital Income)
- Step 6: Crush Debt While You Save
- Step 7: Gamify It With Savings Challenges
- What If Your Income Is Irregular? (The Percentage Method)
- Starting Late in the Year? Your 3-Option Game Plan
- 5 Costly Mistakes That Sabotage Your Savings
- Where Should You Keep Your $10,000?
- What to Do After You Hit $10,000
- Frequently Asked Questions
Is It Actually Possible to Save $10,000 in a Year?
YES — 100%! Everyday individuals and busy families accomplish this goal every single year, and you can too.
The biggest stumbling block is psychology: staring down a giant five-figure sum causes instant analysis paralysis. But nobody saves $10,000 in a single lump sum. You save it $192 at a time, week after week, through steady micro-habits.
The Math: How Much Do You Need to Save?
Here is how $10k breaks down across standard pay cycles:
| Timeframe | Target Amount to Save |
|---|---|
| 📅 Per Year | $10,000.00 |
| 📅 Per Month (12 months) | $833.33 |
| 📅 Bi-Weekly (26 paychecks) | $384.62 |
| 📅 Per Week (52 weeks) | $192.31 |
| 📅 Per Day (365 days) | $27.40 |
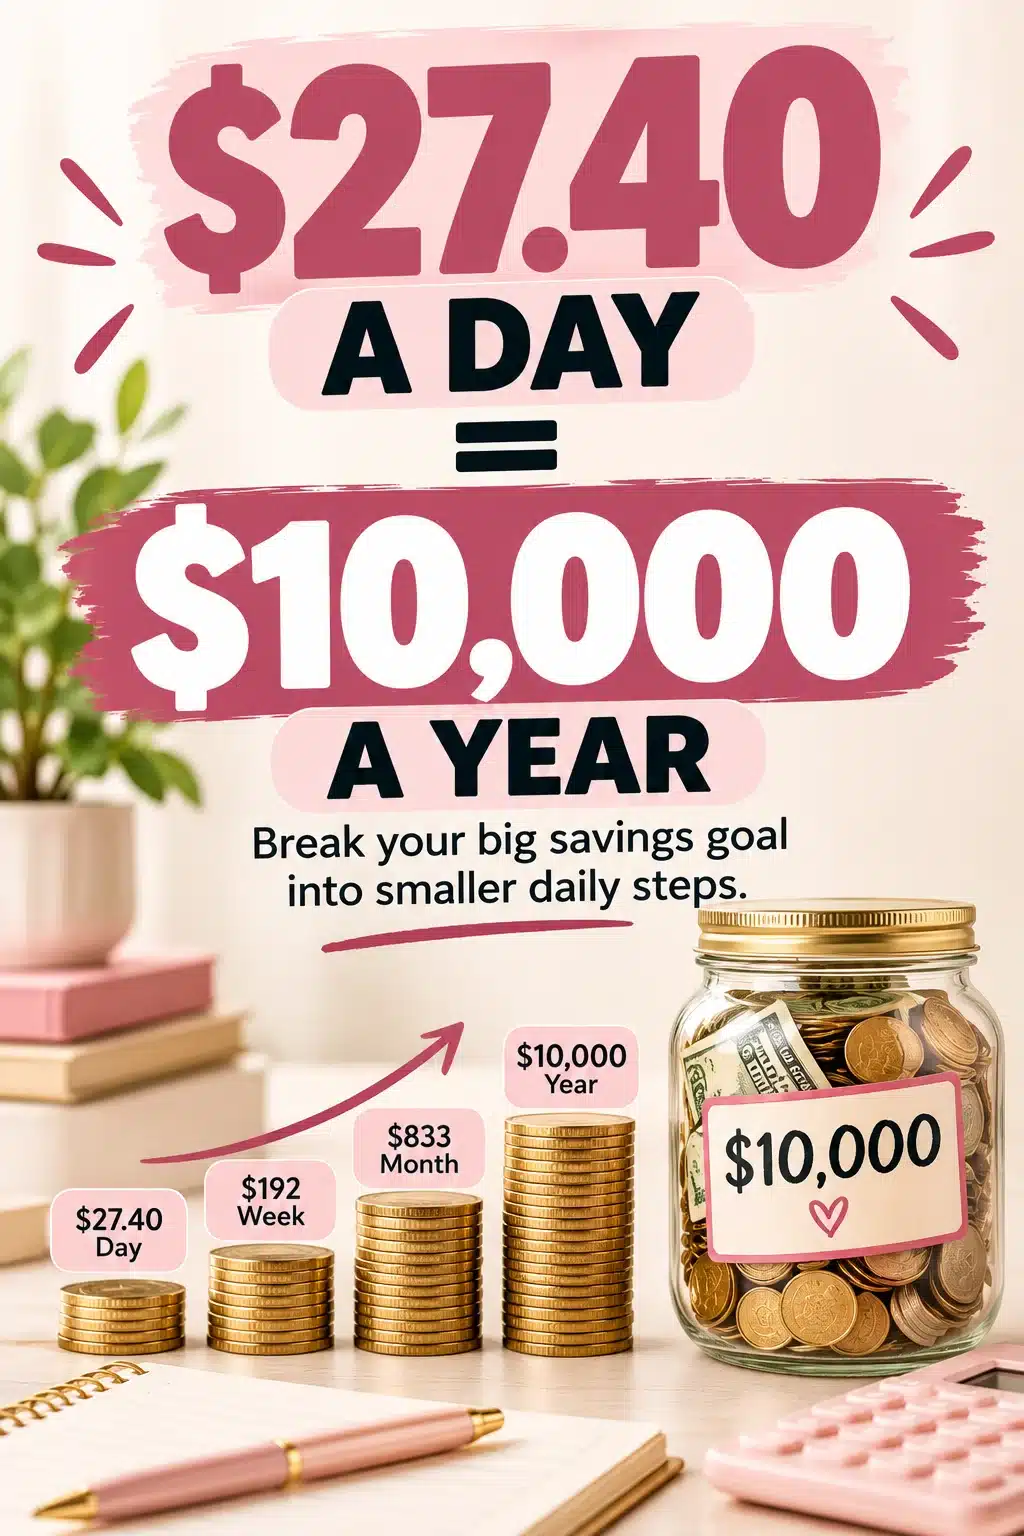
$27.40 a day. That is less than ordering takeout dinner for two! When you frame the challenge as finding $27 a day, the entire equation shifts from intimidating to completely manageable.
Looking to sprint toward your savings target faster? Here are accelerated timelines:
- 6-Month Sprint: $1,666.67 / month ($384.62 / week)
- 3-Month Blitz: $3,333.33 / month ($769.23 / week)
Step 1: Create a Budget (No Sweat, I Promise!)
A budget is not a financial straightjacket — it is simply a proactive game plan. It tells your dollars where to go instead of leaving you wondering where they vanished at month-end. You cannot reliably save $10,000 without clarity on your cash flow.
If you are starting from scratch, begin with the proven 50/30/20 rule:
- 50% Needs: Rent or mortgage, utilities, core groceries, healthcare, and essential commuting.
- 30% Wants: Dining out, subscription entertainment, hobbies, and personal fun money.
- 20% Savings & Debt: Emergency funds and your dedicated $10,000 challenge transfers.
Want to accelerate your results? Flip the equation into an aggressive 45/15/40 split: allocate 40% toward wealth-building and watch your reserves compound rapidly. If you prefer digital spreadsheets, grab our free guide on how to make a budget in Google Sheets.
Step 2: Audit Your Spending — Find the Leaks 🔍
You cannot optimize what you do not measure. For the next 30 days, track every transaction using your banking app, a notebook, or a spreadsheet. Most households unknowingly bleed hundreds of dollars every month through subtle micro-expenses:
- ☕ Daily coffee runs: $5/day adds up to $1,825/year.
- 🍔 Casual takeout: 3 meals/week at $15/meal totals $2,340/year.
- 📺 Forgotten recurring subscriptions: The average consumer wastes $50–$100/month on apps and streaming channels they rarely open.
- 🛒 Unplanned Target/Amazon carts: Small “$15 impulse buys” drain hundreds every single month.
Uncovering these spending leaks is never about guilt — it is about empowerment. Every dollar you redirect from mindless leaks flows directly into your $10,000 milestone.
Step 3: Pay Yourself FIRST (Automate Everything!)
This is the single most important rule in personal finance. Most people save whatever happens to remain in their checking account at the end of the month. The problem? There is almost never anything left. Lifestyle creep expands to consume whatever cash sits in view.
Flip the sequence: Save first, spend what remains.
Configure an automated recurring bank transfer of $192.31 every week (or $384.62 on bi-weekly paydays) directly into a separate high-yield savings account. When transfers execute automatically, willpower is eliminated from the equation. Out of sight, out of mind!
Step 4: Cut Sneaky Expenses (Without Cutting Joy!)
Sustainable savings habits are not about severe deprivation or surviving on plain rice and beans. Cut the expenses you will not even notice missing:
1. The Subscription Purge
Audit all active subscriptions: streaming networks, gym memberships, mobile app trials, and monthly beauty boxes. Cancel anything you haven’t opened in 30 days. This single audit immediately frees up $50–$150/month. Take full advantage of your local public library for free digital audiobooks, e-books via Libby, and free movie streaming through Hoopla.
2. Negotiate Recurring Utility & Insurance Bills
Spend 20 minutes calling your internet service provider, cell phone carrier, and auto insurance agent to request current promotional rates or policy discounts. Comparing insurance quotes online can easily save $300–$600 per year for identical coverage.
3. The Food Budget Revolution
Groceries and dining out represent the biggest variable budget category for most families. Cooking at home just 3 extra nights a week and packing brown-bag lunches saves $200–$300 every month — providing over a third of your annual $10,000 goal through a single lifestyle tweak.
4. Shrink Utility Inefficiencies
Adjust your smart thermostat by 2 degrees, switch older fixtures to energy-efficient LED bulbs, and use smart power strips to cut “vampire power” draw from idle appliances. These small adjustments return $40–$80/month to your savings account.
Step 5: Earn MORE (Because There’s a Limit to Cutting!)
There is a hard mathematical floor to how much you can cut from your living expenses, but there is zero ceiling on how much you can earn. Frugality protects your baseline; income growth builds true financial independence.
A few proven, accessible ways to boost your cash flow:
- 💻 Start a Niche Blog: Building an intentional content site enabled me to scale from $0 to over $10,000/month in affiliate revenue and digital product sales.
- 🛍️ Declutter for Immediate Cash: A weekend decluttering garage sale or Facebook Marketplace purge easily nets $250–$1,000 in cash from unused electronics, clothing, and home furniture.
- 🐕 Flexible Remote or Local Gigs: Pet-sitting on Rover, freelance writing, transcription, or providing remote admin support. For high-demand remote services, see our breakdown on virtual assistant jobs for moms.
- 📌 Pinterest Virtual Assisting: Digital brands pay $300–$800/month per client for creative Pin scheduling and graphic creation — explore how in our guide to making money with Canva.
- 📦 Sell Digital Printables: Create functional planners or budgeting templates once and sell them repeatedly on Etsy. Check out our blueprint on how to sell printables on Etsy.
Bringing in an extra $200 to $400 every month covers nearly half of your $10,000 challenge requirement. Need more inspiration? Check out our list of 23 legit small business ideas from home.
Step 6: Crush Your Debt WHILE You Save
Carrying high-interest revolving credit card debt at 24% APR while attempting to save is like filling a bucket with a hole in the bottom. Before allocating all available cash to your $10,000 savings target, use this sequenced strategy:
The Golden Sequence:
Build an initial $1,000 starter emergency fund first. Next, aggressively attack consumer debt exceeding 7–8% interest. Once high-interest balances are eliminated, direct your full savings rate toward completing the $10,000 goal.
Choose the payoff framework that matches your psychology:
- Debt Snowball Method: Pay minimums on everything, throwing extra cash at your smallest balance first. The quick psychological wins build immense momentum.
- Debt Avalanche Method: Target the balance with the highest interest rate first to mathematically minimize total interest paid.
Step 7: Make It FUN With Savings Challenges 🎮
Saving money does not have to feel tedious. Gamifying the journey keeps motivation high throughout all 52 weeks:
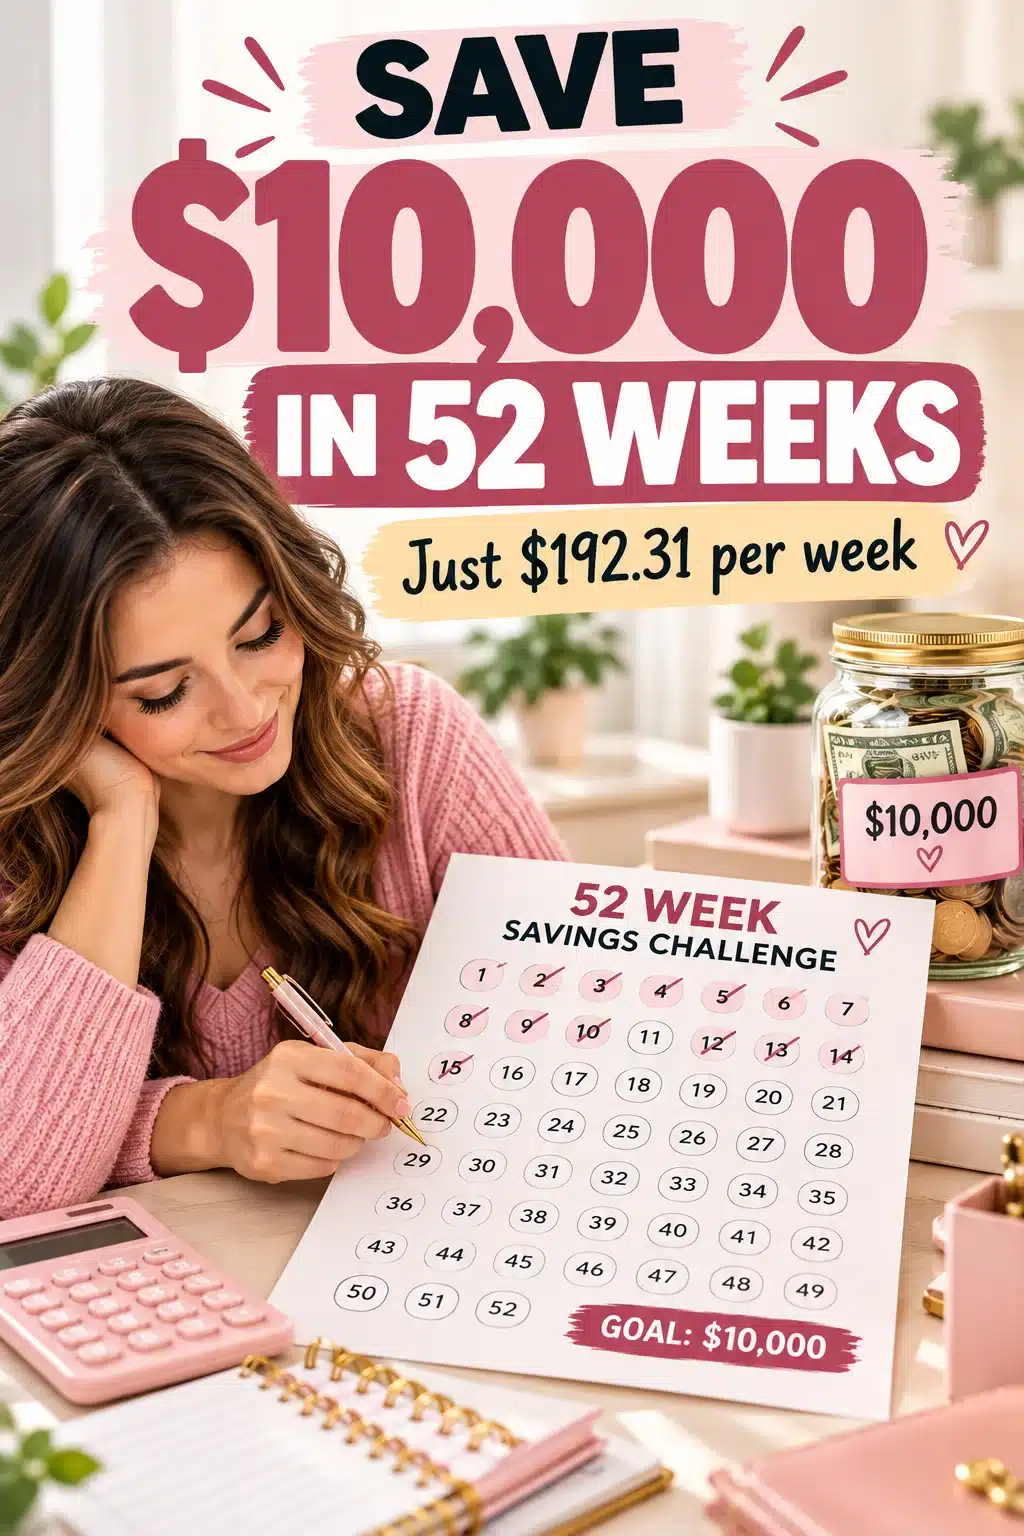
- 📊 The 52-Week Challenge: Transfer $192.31 every week into savings. Color in one block on your printable tracker each Sunday.
- ✉️ The 100-Envelope Challenge: Number 100 envelopes from $1 to $100. Draw one or two envelopes weekly and stuff the corresponding cash amount inside. Completing 100 envelopes yields $5,050 (repeat twice for $10,100!).
- 🚫 The 14-Day No-Spend Challenge: Freeze all non-essential spending for two weeks, purchasing only essential groceries and bills. Most households immediately save $300–$600 while resetting lifestyle habits.
- 🪙 Micro-Deposit Round-Ups: Use micro-savings apps that automatically round everyday debit purchases up to the nearest dollar and transfer the spare change to savings.
What If Your Income Is Irregular? (The Percentage Method)
If you are a freelancer, gig worker, server, or commission-based earner, fixed weekly amounts can feel stressful. Instead, use the Percentage Method:
- Establish a baseline floor: Set a modest minimum savings amount (e.g., $50) transferred from every single paycheck, no matter what.
- Save 30% of above-baseline earnings: Whenever you receive a larger commission or project payout, deposit 30% of everything earned above your baseline directly into savings.
Example: Baseline living costs: $2,500/month with a $350 savings floor. If you earn $3,500 during a peak month, transfer your $350 floor + 30% of the $1,000 surplus ($300) = $650 saved that month. High months build reserves; slower months protect the habit.
Starting Late? Here’s Your Game Plan
If you are starting this challenge later in the year, do not wait until January 1st to begin. Starting today beats waiting for someday every time:
- Option A (Recalculate Remaining Weeks): Divide $10,000 by the weeks left. If you have 16 weeks remaining, aim for $625/week through aggressive spending cuts paired with side hustle income.
- Option B (Build a $2,500 Milestone): Target $2,500 by New Year’s ($208/week). Securing a quick, tangible win builds the habit before tackling the full $10K challenge.
- Option C (Your Personal 365-Day Calendar): Forget the traditional calendar year! Your 12-month timeline runs 365 days starting today. The best time to start was last year; the second best time is right now.
5 Mistakes That Will Sabotage Your $10,000 Goal 🚫
- Saving “Whatever Is Left”: There will never be money left over without intentional automation. Pay yourself first.
- Leaving Savings in Checking: If savings sit in your primary spending account, you will inevitably spend them. Transfer funds out of sight.
- Demanding Absolute Perfection: An unexpected car repair or medical bill is not failure. Recalculate your timeline, adjust, and keep moving forward.
- Failing to Track Weekly Progress: What gets measured gets managed. Use your visual tracker to stay accountable.
- Comparing Your Timeline to Social Media: Someone else saved $20K in 6 months? Focus strictly on your own goals and celebrate your personal milestones.
Where Should You Keep Your $10,000? 🏦
Keep your challenge funds in a High-Yield Savings Account (HYSA) — never your standard checking account. Here is why:
- Earns 4–5% APY: A traditional checking account yields ~0.01%, while an HYSA pays $400–$500+ in passive interest on a $10,000 balance.
- Creates Helpful Friction: Moving money from an external savings account takes 1–2 business days, preventing impulse spending while keeping cash liquid for true emergencies.
- 100% FDIC Insured: Fully insured up to $250,000 per depositor by the Federal Deposit Insurance Corporation (FDIC). Check current rate comparisons on NerdWallet’s HYSA guide.
What to Do After You Hit $10,000 🎉
Congratulations — you hit your goal! Now protect that capital from inflation and put it to work:
- Secure 3–6 Months of Living Expenses: Leave a foundational emergency reserve untouched in your HYSA.
- Eliminate Any Lingering Debts: Wipe out remaining car loans or student balances.
- Begin Low-Cost Index Investing: Put surplus money into broad market index funds (like total stock market ETFs) so compound interest compounds your wealth.
- Define Your Next Milestone: A home down payment, starting a business, or building toward early financial independence.
Frequently Asked Questions
Is it realistic to save $10k in a year?
Yes! Breaking $10,000 into $192.31/week or $27.40/day makes the target completely achievable when combining modest spending trims with an extra income stream.
What if I can’t save $833 every single month?
Save what you can. Saving $500/month still builds a life-changing $6,000 cash cushion. Consistent progress beats perfection every time.
Should I save $10K or pay off debt first?
Build a $1,000 emergency buffer first, aggressively pay down toxic consumer debts with interest rates above 7–8%, and then direct your full savings rate toward the $10,000 challenge.
Can I save $10,000 on a low or irregular income?
Yes. Use the percentage method: automate a baseline floor amount from every payment, save 30% of windfalls and bonuses, and add a flexible home-based micro-side hustle.
What if I fall behind schedule?
Recalculate! Divide your remaining balance by the weeks left, adjust your weekly transfer, or extend your timeline by 60 days. The only true failure is quitting entirely.
Quick Recap: Your $10,000 Savings Game Plan
- Know your numbers: $833/month, $192/week, or $27.40/day
- Set up your budget: Use the 50/30/20 framework
- Audit your accounts: Identify and eliminate recurring leaks
- Automate savings: Pay yourself first into an FDIC-insured HYSA
- Trim painless expenses: Purge unused apps, cook more at home, negotiate bills
- Expand your earnings: Start a blog, sell printables, or freelance
- Crush high-interest debt: Protect progress with a $1,000 emergency fund
- Gamify the challenge: Color in your tracker weekly
Saving $10,000 in a year is completely within your reach. Open that high-yield savings account today, print your challenge tracker, and set up your first automatic transfer. One year from now, you will look back with incredible pride. You’ve got this!
📖 Keep Reading